Estate planning in Westport, CT works when the documents and the accounts tell the same story. Westport Wealth Partners coordinates the financial side of your estate plan with your estate attorney and CPA: beneficiary designations, account titling, trust funding, gifting and the liquidity an estate will need, all aligned with the plan your attorney drafts.
For many Fairfield County and Westchester families, the weak point is not the will. It is the retirement account with an outdated beneficiary, the brokerage account titled the wrong way, or the trust that was signed but never funded. Those gaps are financial, and they are the part of estate planning a wealth advisor sees every day.
Raymond James does not provide tax or legal services. Your estate attorney drafts and updates wills, trusts and powers of attorney, and your CPA prepares the tax filings. Our role is to help keep the financial side of the plan aligned with those documents, and to give your attorney and CPA the complete picture they need to advise you.
Schedule a Conversation About Your Estate Plan
No obligation. One meeting to see how your accounts, beneficiaries and estate documents line up.
If Your Estate Plan Was Signed Years AgoSigns the Documents and the Accounts No Longer Match
If your wills were signed ten or fifteen years ago, before a business grew, a child married or you moved into or out of Connecticut, you are describing the family estate planning coordination is built for. The documents may still be valid. The question is whether your accounts still carry them out. A review starts with your current documents and every account, side by side.
Several signs suggest the financial side of a plan has drifted:
- Beneficiary forms on 401(k)s and IRAs were completed when the accounts were opened and never revisited.
- A revocable trust exists, but the brokerage and bank accounts are still in individual names.
- A former spouse, a late parent or a minor child is still listed somewhere.
- A business has grown into the largest asset in the estate, and no one has asked how it would pass, or how the estate would pay what is owed while it does.
Tax law has also moved. For deaths in 2026, the federal basic exclusion amount is $15 million under Public Law 119-21, and Connecticut ties its own exemption to that figure 1,3. New York's exclusion for 2026 is $7,350,000 4. A plan built around the numbers of a decade ago may be organized around the wrong thresholds.
None of these issues requires starting over. Many are resolved by aligning the accounts with the plan your attorney already wrote, or by bringing a specific question back to your attorney with the financial facts in hand. That is the work we coordinate.
Connecticut's Estate and Gift Tax in 2026What the $15 Million Exemption Reaches
Connecticut has its own estate and gift tax, separate from the federal system. For deaths in 2026, the Connecticut Department of Revenue Services sets the exemption at $15 million, the same as the federal basic exclusion amount, and the tax is 12% of the Connecticut taxable estate above it 1,2,3. The combined Connecticut estate and gift tax is capped at $15 million 2.
Three details matter for planning:
- Connecticut adds back taxable gifts made since January 1, 2005, so lifetime gifts above the annual exclusion are counted when the estate is measured 2.
- Connecticut taxes gifts during life as well as transfers at death, which is why gifting is planned with the estate attorney rather than on its own.
- A filing can be required even when no tax is due: an estate of $15 million or less files Form CT-706 NT with the Probate Court for the district where the decedent lived 1.
Unlike New York, Connecticut has no fixed three-year lookback for gifts. It counts every Connecticut taxable gift made since 2005, and it also adds back any gift tax paid on gifts made in the three years before death, with the gift tax already paid credited against the estate tax 2. Lifetime gifting can still serve a family's goals, but in Connecticut it is planned for what it accomplishes, not as a way around the estate tax.
Probate Court fees are a separate cost, set by statute on a schedule tied to the size of the estate, and they reach $40,000 for estates of $8,877,000 and over 7. We help estimate these costs alongside the tax so the estate's liquidity plan reflects both.
New York's Estate Tax and the 105% CliffWhy Families With New York Ties Plan Differently
New York's estate tax reaches far smaller estates than the federal or Connecticut tax. New York's basic exclusion amount for 2026 is $7,350,000, about half the Connecticut and federal figure, according to the New York State Department of Taxation and Finance 4.
The structure is what surprises families. New York phases out its credit between 100% and 105% of the exclusion amount, so a New York taxable estate above 105%, about $7.7 million for 2026, loses the credit and can owe tax on its full value rather than only on the excess 5. An estate a few hundred thousand dollars over the line can owe far more than one just under it.
New York has no gift tax; it was repealed for gifts made on or after January 1, 2000 6. It does add back taxable gifts made within three years of death, with limited exceptions, a rule now extended to deaths before January 1, 2032 4. For Westchester families, and for Connecticut residents with ties to New York, these rules are worked through with the estate attorney, and we bring the financial picture that the planning depends on.
Because the cliff turns on the size of the New York taxable estate, the planning questions are often financial ones: how assets are titled, where real property sits, how retirement accounts and insurance are designated, and how gifts are timed. Those are the questions we work through with your attorney and CPA, with current account values rather than estimates.
Estate Planning Areas We Coordinate
Estate planning coordination covers six financial areas that support the plan your attorney designs. These are not legal or tax services. They are financial planning disciplines, carried out with your estate attorney and CPA, that decide whether the plan works when it is needed.
Retirement accounts and life insurance generally pass by beneficiary designation, outside the will, and jointly titled accounts pass by title. We review every designation and title across your accounts so they reflect your current wishes and the structure your attorney has drafted, including contingent beneficiaries and any trust named as a beneficiary.
A trust holds only what is moved into it. We help coordinate the retitling of the accounts your attorney designates for a trust, confirm what has and has not been funded, and manage trust assets in line with the trust's terms and the beneficiaries' time horizon.
For 2026, the federal annual gift tax exclusion is $19,000 per recipient, according to the IRS 3. We model how annual gifts, education funding and larger lifetime gifts fit your cash flow and your estate plan, with Connecticut's treatment of taxable gifts in view 2.
For families with charitable goals, we coordinate giving approaches, such as gifts of appreciated securities or a donor-advised fund, with the estate plan and with your CPA, so charitable decisions and family decisions are made together.
Estate taxes, Probate Court fees and settlement costs can come due before illiquid assets such as a business or real estate are sold 1,7. We help estimate the liquidity an estate may need and plan where it would come from, in coordination with your attorney.
Families with ties to both Connecticut and New York, or with property in more than one state, can face more than one estate tax system 1,4. We coordinate with your attorney on how residency and property location affect the plan.
Estate Planning for Business OwnersWhen the Company Is the Largest Asset in the Estate
When the largest asset is a private business, the estate plan and the exit plan are the same conversation. A company that cannot be sold quickly can leave heirs with taxes, Probate Court fees and settlement costs to cover and no simple way to cover them 1,7.
Matthew T. Streif, CEPA® and Nicholas DiFalco, APMA® CEPA® work with business owners for whom the company is the retirement plan. Their exit planning work, built on the Certified Exit Planning Advisor credential from the Exit Planning Institute, addresses the questions an estate plan has to answer as well: who will own the business, how ownership will transfer, what it is realistically worth to a buyer, and what the family will live on if it is sold or if the owner can no longer run it.
In practice that means coordinating succession and buy-sell decisions with the estate attorney, modeling how the timing of a sale affects what passes to family, and planning the liquidity an estate would need if the business is still held at death. Raymond James and its advisors do not offer tax, legal or business valuation advice; those decisions are made with your attorney and CPA.
The Coordination ModelHow This Works Alongside Your Attorney and CPA
Coordination means one complete financial picture, shared with the professionals who need it. Your estate attorney leads the legal plan, your CPA leads the tax filings, and we keep the accounts, titles and cash flow aligned with both. In practice, this looks like:
A complete list of your accounts, titling, beneficiary designations, insurance and business interests, compared against your current wills and trusts. Gaps are flagged in plain language: an account outside the trust, a form that names someone it should not, an asset with no plan for how it passes.
A written summary for your estate attorney and CPA, so legal and tax recommendations are made with the full financial picture rather than a partial one. With your permission, we join the conversation with your attorney or CPA directly.
The financial steps your attorney's plan calls for: beneficiary updates, account retitling, trust funding and the gifting schedule, each confirmed back to you and your attorney once it is complete.
Reviews scheduled at your desired frequency, and after life events such as a marriage, a birth or a death in the family, a move to another state or the sale of a business.
Who Coordinates Your Estate Plan at Westport Wealth PartnersThree Partners, One Coordinated Plan
Estate planning coordination at Westport Wealth Partners is led by the practice's three Managing Partners, each a Wealth Advisor with Raymond James Financial Services (RJFS). Together they bring portfolio management, exit planning and retirement income experience to the financial side of an estate plan. Each partner's registration history is available on FINRA BrokerCheck.
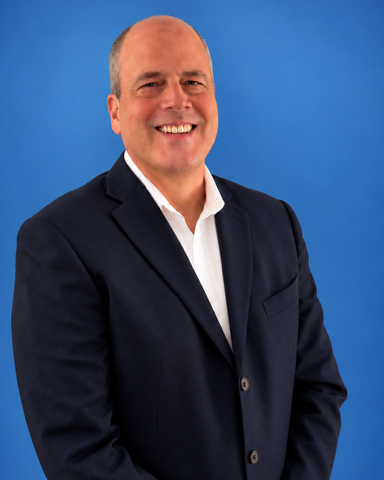
Nicholas DiFalco, APMA® CEPA® holds the Accredited Portfolio Management Advisor℠ designation from the College for Financial Planning, a Kaplan Company, and the Certified Exit Planning Advisor designation from the Exit Planning Institute. He works with business owners whose wealth is concentrated in a company. In his words: "It is not just about the market. There are tax-aware planning considerations, risk management, and broader financial planning decisions that can add value."
Meet Nick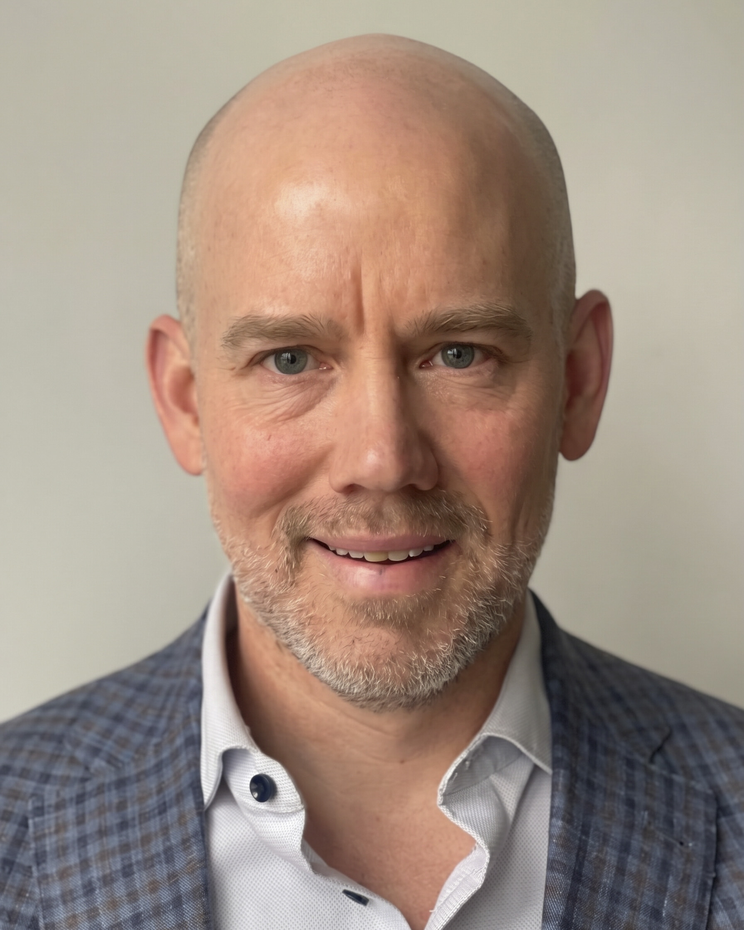
Matthew T. Streif, CEPA® spent 21 years as a Financial Advisor at Morgan Stanley and UBS, leaving both as a Senior Vice President, and holds a BBA and an MBA from the University of Texas at Austin. His work centers on business owners planning a transition.
Meet Matt
Scott E. Kelly has 26 years in financial services, holds the Series 7 and Series 65 registrations, and is licensed for variable life and health insurance. He works with clients in or near retirement on income they cannot outlive, with the goal that each client can explain to a family member what they own and why.
Meet ScottFrequently Asked Questions About Estate Planning
Does Westport Wealth Partners draft wills or trusts?
No. Raymond James does not provide tax or legal services. Wills, trusts and powers of attorney are drafted by your estate attorney. We coordinate the financial side of the plan: investments, account titling, beneficiary designations, trust funding and the cash flow behind gifting decisions, and we share that picture with your attorney and CPA.
Does Connecticut have an estate tax in 2026?
Yes. For deaths in 2026, the Connecticut estate tax exemption is $15 million, the same as the federal basic exclusion amount, and the tax is 12% of the Connecticut taxable estate above it, according to the Connecticut Department of Revenue Services 1,2,3. The combined Connecticut estate and gift tax is capped at $15 million 2. An estate of $15 million or less still files Form CT-706 NT with the Probate Court 1.
We live in Westchester. How is New York's estate tax different?
New York's 2026 basic exclusion amount is $7,350,000 4. New York phases out its credit between 100% and 105% of that amount, so an estate more than 105% of the exclusion loses the credit and is taxed on its full value 5. New York has no gift tax, but it adds back taxable gifts made within three years of death, with limited exceptions 4,6. Your estate attorney can explain how these rules apply to you.
Should I update my will or my beneficiary designations first?
They work together, so the order is usually decided with your attorney. Beneficiary designations on retirement accounts and life insurance generally control those assets regardless of what the will says, so an outdated form can override an updated will. A common sequence is to confirm the plan with your attorney, then update the designations and titling to match it.
I'm the executor of a parent's estate. Can you help?
Your parent's estate attorney leads the legal work of settling the estate, and the Probate Court oversees it. We can help with the financial side: an inventory of accounts, how they are titled and who the named beneficiaries are, and the liquidity the estate needs for taxes, Probate Court fees and settlement costs 1,7, coordinated with the attorney.
Why coordinate estate planning with a financial advisor?
In our opinion, many estate plans fall short not because of the documents but because of what happens after they are signed. New accounts are opened, beneficiaries change, and assets are never moved into the trust. Coordinating the estate plan with the financial plan helps keep the two aligned over time, with your attorney and CPA working from the same picture.
How often should an estate plan be reviewed?
There is no single schedule. We review the financial side of the plan at the frequency you prefer, and we suggest a review after events that change the picture: a marriage or divorce, a birth or death in the family, a move to another state, a large inheritance or the sale of a business. Changes in tax law are another reason to revisit the plan with your attorney.
What should I bring to a first conversation?
A list of your accounts and their approximate values, recent statements, current beneficiary designations, copies of any wills or trusts, and information about business interests or property in other states. If you work with an estate attorney or CPA, their contact information helps us coordinate from the start.
Related pages on this site
Any opinions are those of the author, are subject to change without notice and are not necessarily those of Raymond James. This information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation. The information has been obtained from sources considered to be reliable, but we do not guarantee that the foregoing material is accurate or complete. Every investor's situation is unique and you should consider your investment goals, risk tolerance and time horizon before making any investment. Investing involves risk and you may incur a profit or loss regardless of strategy selected, including diversification and asset allocation. Prior to making an investment decision, please consult with your financial advisor about your individual situation. Be sure to contact a qualified professional regarding your situation before making any investment or withdrawal decision. Raymond James and its advisors do not offer tax or legal advice. You should discuss any tax or legal matters with the appropriate professional.
Tax laws, deal structures, legal agreements, valuation methods, and market conditions are complex and subject to change. You should consult your own qualified tax advisor, attorney, and financial professional before making any investment decision. Raymond James and its financial advisors do not provide tax, legal or business valuation advice.
Donors are urged to consult their attorneys, accountants or tax advisors with respect to questions relating to the deductibility of various types of contributions to a Donor-Advised Fund for federal and state tax purposes. To learn more about the potential risks and benefits of Donor Advised Funds, please contact us.
Sources:
1. Connecticut Department of Revenue Services, Estate and Gift Taxes: Tax Information. https://portal.ct.gov/DRS/Individuals/Individual-Income-Tax-Portal/Estate-and-Gift-Taxes/Tax-Information (accessed November 4, 2026)
2. Connecticut General Statutes, Chapter 217, Sec. 12-391. https://www.cga.ct.gov/current/pub/chap_217.htm (accessed November 4, 2026)
3. Internal Revenue Service, What's New: Estate and Gift Tax. https://www.irs.gov/businesses/small-businesses-self-employed/whats-new-estate-and-gift-tax (accessed November 4, 2026)
4. New York State Department of Taxation and Finance, Estate Tax. https://www.tax.ny.gov/pit/estate/etidx.htm (accessed November 4, 2026)
5. New York State Department of Taxation and Finance, TSB-M-14(6)M. https://www.tax.ny.gov/pdf/memos/estate_&_gift/m14_6m.pdf (accessed November 4, 2026)
6. New York State Department of Taxation and Finance, Gift Tax. https://www.tax.ny.gov/forms/prvforms/gift_tax_1983_1999.htm (accessed November 4, 2026)
7. Connecticut General Statutes, Chapter 801b, Sec. 45a-107. https://www.cga.ct.gov/current/pub/chap_801b.htm (accessed November 4, 2026)